
The short version Taigang and Tsingshan both cut their August high-carbon ferrochrome purchase prices by another RMB 200 per 50 base tonne. The cost floor under 430 cold rolled just dropped again. But 400-series inventory has fallen two weeks running and mills have maintenance scheduled for month-end. So 430 is cheaper to make and scarcer to buy. Lock volume in tranches. Don’t bet the quarter on one move.
What happened
Ferrochrome has had a rough half year.
Domestic high-carbon ferrochrome drifted from RMB 8,100 down toward RMB 8,000 per 50 base tonne through July. August opened with another cut. Taigang set its August purchase price at RMB 7,895 per 50 base tonne (cash, tax included, delivered) — RMB 200 below July. Tsingshan set its August long-term contract price at RMB 8,095 per 50 base tonne (cash, tax included, delivered), with the Tianjin Port receiving price a further RMB 150 lower, also down RMB 200 month on month. When both bellwether tenders break below 8,100, the psychological line goes with them.
Spot followed. On 5 August the market range narrowed to RMB 7,950–8,100 per 50 base tonne. Mysteel quoted Inner Mongolia Cr50% ex-works, tax included, at RMB 7,925 per 50 base tonne on 7 August — down another 75 that day. Spot tenders looked worse still: one Hunan mill took just 1,000 tonnes at RMB 8,350 per 50 base tonne on tax-inclusive acceptance, down 120.
On the finished side, 430 looks steady by comparison. Wuxi 430 cold rolled is quoted at RMB 7,700–7,750 per tonne, 430 hot rolled at RMB 6,900 per tonne — both flat week on week. Foshan’s JISCO 430 cold rolled mill-edge base price sits at RMB 7,600 per tonne. Inventory is drawing down: Wuxi 400-series spot stock stands at 138,800 tonnes, off 400 tonnes on the week, with cold and hot rolled falling together for a second straight week.
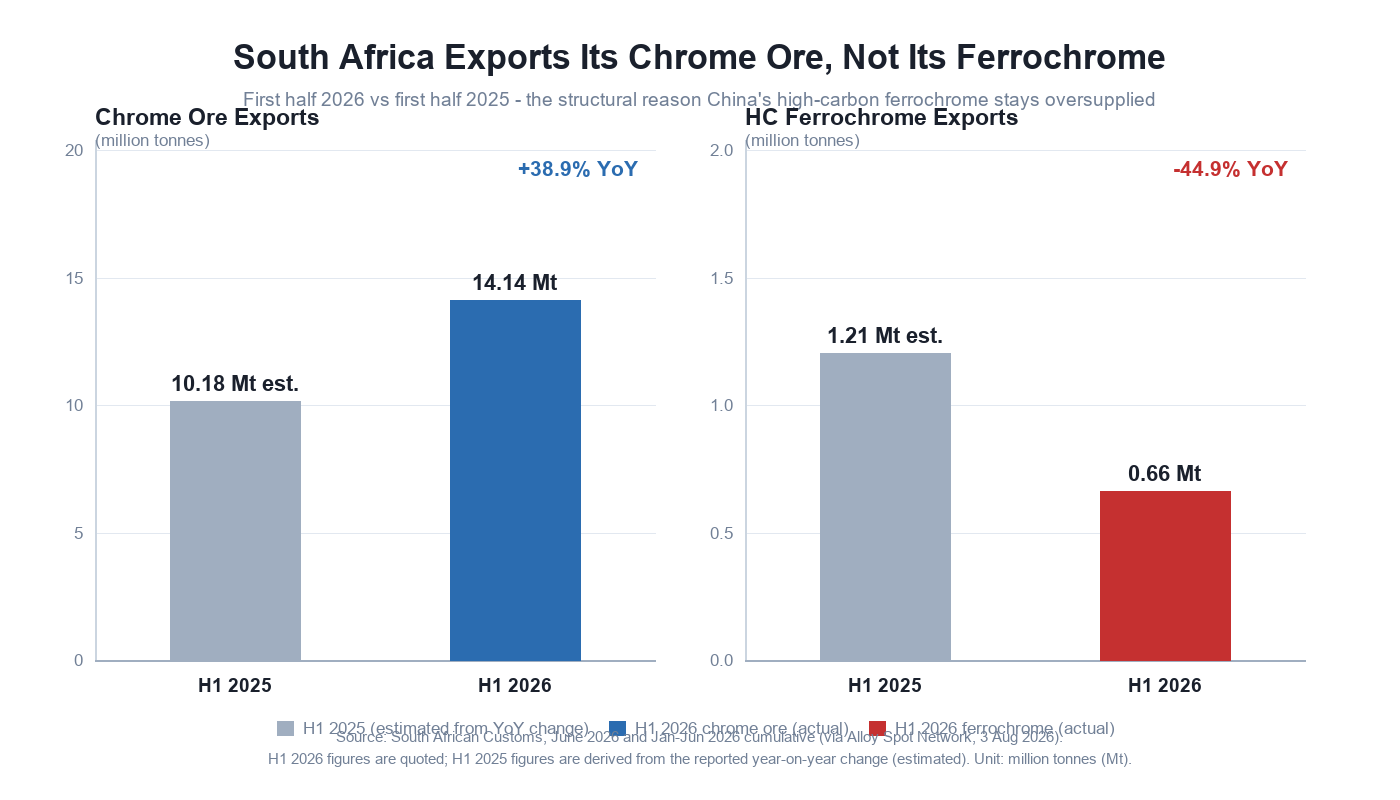
The interesting number is South African. In January–June 2026, South Africa exported 663,900 tonnes of high-carbon ferrochrome, down 44.9% year on year. Over the same period it exported 14.1443 million tonnes of chrome ore, up 38.9%. Ore out, alloy not — South Africa has handed the smelting step to China, and Chinese ferrochrome supply stays structurally long as a result. That, not one slow month, is why ferrochrome cannot rally.
| Data point | Value | Date | Basis | Source |
|---|---|---|---|---|
| Taigang August HC ferrochrome tender | RMB 7,895/50 base t (cash, tax incl., delivered), −200 MoM | 2026-08 | Cited | 51bxg |
| Tsingshan August HC ferrochrome contract | RMB 8,095/50 base t (cash, tax incl., delivered), −200 MoM | 2026-08 | Cited | 51bxg |
| HC ferrochrome market price | RMB 7,950–8,100/50 base t | 2026-08-05 | Cited | Alloy Spot |
| HC ferrochrome Cr50% Inner Mongolia | RMB 7,925/50 base t (−75) | 2026-08-07 | Cited | Mysteel |
| Chrome concentrate Cr40-42% South Africa | CIF USD 281.5/t | 2026-08-07 | Cited | Mysteel |
| 430 cold rolled (Wuxi) | RMB 7,700–7,750/t, flat WoW | 2026-08-08 | Cited | Gougang |
| 430 hot rolled (Wuxi) | RMB 6,900/t, flat WoW | 2026-08-08 | Cited | Gougang |
| Wuxi 400-series spot inventory | 138,800 t, −400 t WoW, second straight weekly fall | week of 2026-08 | Cited | 51BXG |
| South Africa HC ferrochrome exports | H1 663,900 t (−44.9% YoY) | 2026 | Cited | SA Customs |
| South Africa chrome ore exports | H1 14,144,300 t (+38.9% YoY) | 2026 | Cited | SA Customs |
| China August stainless crude steel schedule | 3.6388 million t, +44,400 t MoM | 2026-08 | Cited | Mysteel |
| 200-series coordinated cut | August market release down 20% combined | 2026-08 plan | Cited | Mysteel |
| August HC ferrochrome expected range | RMB 7,800–8,100/50 base t | 2026-08 | Cited (forecast) | Lange Steel |
What it means for buyers
One: the cost floor under 430 is falling, but slowly. Ferrochrome is down about RMB 300 per 50 base tonne over two months. Translated into 430 cold rolled, that is roughly RMB 100–150 per tonne (estimate, using a conventional 16–18% chrome charge). And 430 cold rolled quotes haven’t moved in two weeks. The mill kept the difference.
Two: supply is quietly tightening. Total output is up — August stainless crude steel is scheduled at 3.6388 million tonnes, 44,400 tonnes more than July. But the mix has shifted. Three mills coordinated a 20% cut in 200-series August market release, 400-series maintenance is planned for month-end, and Wuxi 400-series inventory has fallen two weeks straight. So 430 will not collapse just because ferrochrome fell. Shrinking availability is holding it up.
Three: don’t expect a ferrochrome rebound. Chrome ore exports up 38.9% against ferrochrome exports down 44.9% means domestic Chinese smelters keep getting fed. Add the third round of coke price cuts that began on 5 August and the cost line is still moving down. The forecast August range of RMB 7,800–8,100 per 50 base tonne is a bottom, not a base for a rally.
Impact by product and region
| Grade / market | Current price | Outlook | Buyer action |
|---|---|---|---|
| 430 CR coil/sheet | Wuxi RMB 7,700–7,750/t; Foshan RMB 7,600/t | Soft-stable, RMB 7,600–7,800/t (estimate) | Lock in tranches, max 30 days’ usage per tranche |
| 430 HR coil/sheet | Wuxi RMB 6,900/t | Follows CR, spread stable | Same as above |
| 409L / automotive exhaust | Tracks 430, lower chrome content | Cost relief transmits faster | Negotiate this one first |
| 201 J1/J2/J5 CR | J1 approx. RMB 8,500–8,600; J2/J5 approx. RMB 7,600–7,700/t | 20% 200-series cut supports price | Do not trade the “off-season must fall” reflex |
| 304 CR (reference) | Wuxi RMB 14,800/t | Driven by nickel and Indonesian quota — a different market | Quote the two lines separately. No linkage. |
| Europe | China flat-product country quota 49,946 t/yr (Cat8 HR 9,515 + Cat9 CR 40,431); 50% out-of-quota tariff | Quarterly, first come first served | 430 is a flat product and draws on the same quota |
| South Africa / chrome ore | Chrome concentrate CIF USD 281.5/t | High port stocks, hard to hold price | If ore doesn’t rise, 430 has no cost push |
What to do now
- Lock 430 in tranches. Don’t go all in. One tranche per 30 days of usage; add another each time ferrochrome falls a further RMB 100 per 50 base tonne. The floor is dropping but supply is tightening — a one-way call is risky.
- Take the ferrochrome tender numbers into your 430 negotiation. Taigang 7,895 and Tsingshan 8,095 are public, down 200–300 across two months. Your 430 quote hasn’t moved. That is a documented ask.
- Split 300-series and 400-series buying rhythms completely. 304 follows Indonesian RKAB quotas and nickel; 430 follows ferrochrome tenders and South African export structure. They decoupled this year. One logic will get you the wrong answer on one of them.
- Book the EU clearance window early. 430 cold rolled falls under Cat9, with a 40,431-tonne annual Chinese quota. Miss the first two weeks of the quarter and the tariff is 50%.
- Three signals to turn bullish: South African HC ferrochrome exports turn positive month on month; chrome ore port stocks start drawing down; Wuxi 400-series inventory falls four weeks running. Two out of three before you build stock.
How Still Steel Supports the Project
Still Steel supplies stainless steel coil, strip and sheet with slitting, cut-to-length, brushing, polishing and protective-film services.
Send the grade, dimensions, annual volume and application to vip@still-steel.com, or discuss the requirement on WhatsApp.